
Equipment and process
Logging Equipment
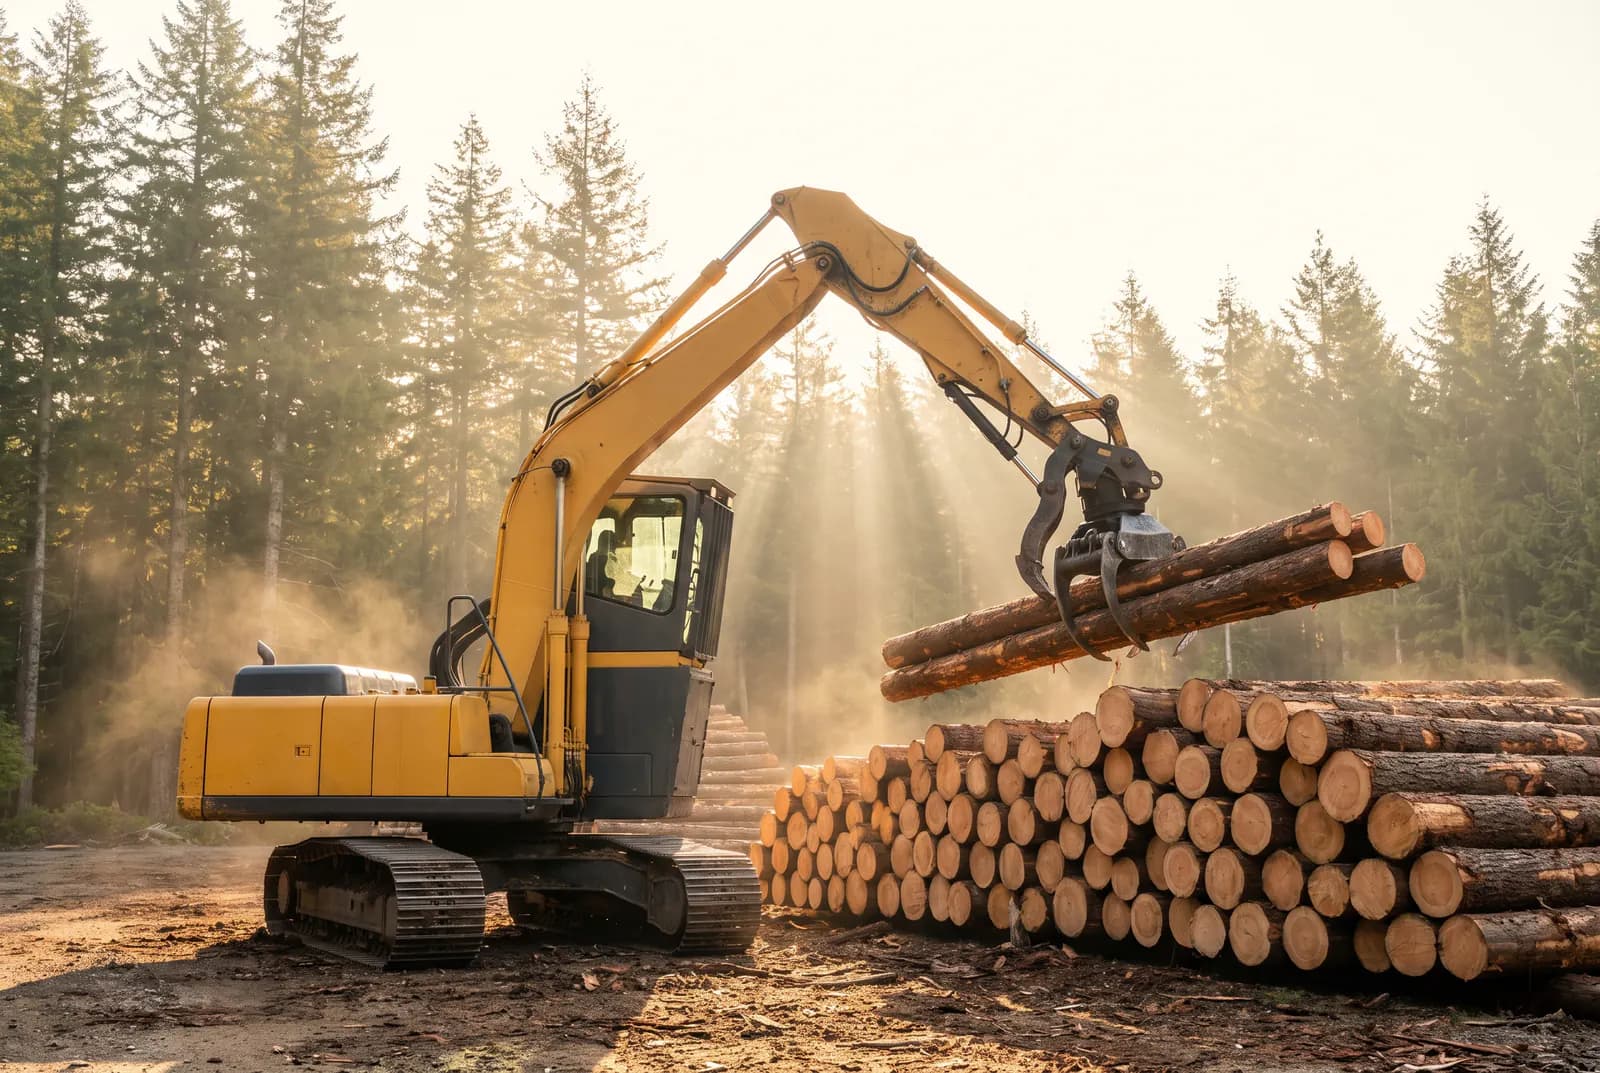
Skidders, processors, log loaders, and log trucks. Lenders that price logging's seasonality and weather risk rather than turning the deal down over them.
What we finance
Why JCF for logging
Yellow iron, trucking, and logging are JCF's three named specialties. Logging gets the same lender access as the larger categories, not a generic equipment quote.
Banks tend to avoid logging because of weather risk, seasonality, and resale dynamics. JCF works with lenders that price those factors instead of declining over them.
Based in Vancouver, WA, with dealer relationships across Oregon, Washington, Idaho, and Northern California. We know who funds what in this corner of the country.
How financing works
Most logging operations don't earn evenly across twelve months. We work with lenders on adjusted-payment schedules, seasonal skips, or terms that match how the work and the revenue actually land.
Quick primer
An Equipment Finance Agreement (EFA) is one of the most common ways small businesses fund equipment purchases. It looks and feels like a lease, but it's technically not one. With an EFA, you own the equipment from day one, and the lender secures their position with a UCC filing or a title lien.
Because you own it, the equipment shows up on your balance sheet, and you handle depreciation on your end. For most operators, an EFA is a cleaner fit than a lease.
Common questions
Credit matters, but it's one factor among many. Lenders also look at time in business, homeownership, the type of business you run, how many guarantors are on the loan, and your history with similar-sized loans.
Strong credit gets you the best rates. Weaker credit doesn't automatically disqualify you. There are lenders that specialize in B, C, and D credit tiers, and we work with them when it makes sense for your situation.
A collateral loan uses other lien-free equipment you already own as security for new financing. It's a common tool when your credit profile or time in business makes a lender hesitant on the deal alone.
Lenders typically want a two-to-one ratio. To borrow $30,000 against collateral, you'd put up roughly $60,000 in lien-free equipment. The exact ratio depends on the lender and the equipment, but two-to-one is a reasonable starting expectation.
Yes. Every commercial loan, EFA, or lease can be paid off ahead of schedule.
That said, commercial loans usually aren't simple-interest the way a personal car loan is. The remaining balance is calculated on a pre-set amortization, so paying off early may not save you as much interest as you'd expect. Ask for a payoff quote before you assume the savings, and we'll walk through the math with you.
Texting is the fastest way to reach us.
Equipment and process
Ready when you are
We review every application personally and get back within one business day.